AECB Credit Score for Mortgage Approval in UAE: What Changed in 2026

AECB Credit Score for Mortgage Approval in UAE: What Changed in 2026

  • Written bySweety Ved,Property Consultant
  • Buyer's Guide
  • Reviewed by Vikas Taneja, RERA Certified Broker, BRN 82127
  • Published: 06 Nov 2026
  • 10 min read
Add us as aPreferred Source

Etihad Credit Bureau launched Credit Score 3i on 29 October 2026, replacing the old 300 to 900 scale that many score charts online are still based on. This guide explains how UAE banks now read your score for a mortgage, which Central Bank limits still cap the loan, and how to clean up your credit report before you apply.

Does your AECB score decide whether a UAE bank approves your mortgage? The honest answer is: it depends on the full file. The bureau score shows a lender how you have repaid debt, while federal rules on income and deposit set the most any bank may lend. A weak score can lead a bank to decline, cut the loan amount or tighten the terms.

At Honey Money Real Estates, we advise buyers to read their own credit report before reserving a unit. If the bank is the first to find a forgotten card balance, an unpaid telecom bill or an old returned cheque, the buyer has to sort it out while the sale deadline is already running.

This guide follows the official Credit Score 3i launch details and the federal mortgage regulations on loan to value and debt burden in force in November 2026.

AECB Score for Home Loan in UAE: How Banks Use It

UAE banks check a borrower's file with the federal credit bureau, still widely known as AECB, before approving property finance. Lenders read the score to judge repayment risk. Central Bank rules fix the maximum anyone can borrow, and the score helps a bank decide whether to offer that maximum, a smaller amount or nothing at all.

The bureau collects monthly data from banks, finance companies, telecom operators and utility providers. A mortgage underwriter reading an AECB report sees active loans and cards, payment delays, returned cheques and court ordered financial obligations. The report does not list bank deposits, investments or property owned, so savings have to be shown to the bank separately.

The bureau makes no lending recommendation. Each bank applies its own credit policy, which is why one lender may approve an applicant that another declines with the same report.

AECB Score Range 2026: Credit Score 3i Explained

Credit Score 3i now gives borrowers with an established credit history a score between 300 and 850. Eligible residents who are new to credit or new to the UAE receive a score between 300 and 650 instead.

What Changed Under the 3i Model

  • Longer look back: the score now looks at up to 36 months of credit behaviour, against 24 months under the previous version.
  • Clearer reports: each report lists the positive and negative factors behind the number, with recommendations to improve it.
  • More data for lenders: banks, finance companies and eligible fintechs now receive a fuller picture of each borrower for their credit risk checks.

Why Older Score Band Charts No Longer Apply

Many guides still show bands such as 746 and above for an excellent rating. Those labels come from bank and website guides written for the old scale, and the bureau does not publish official band names. Since the top of the scale has moved and the model reads a longer history, a number from an old chart is not a fair benchmark for a 3i score.

Minimum Credit Score for Home Loan in Dubai: What Lenders Check

There is no official minimum credit score for a home loan in Dubai. The bureau sets none, and each bank applies its own criteria. What every lender must apply are the Central Bank limits on debt burden and loan to value.

Debt Burden Ratio (DBR) Cap of 50 Percent

Total monthly repayments on all loans and cards, including the new mortgage, cannot exceed half of gross salary plus regular income from a defined source. Lenders are told not to apply that maximum by default.

A buyer earning AED 30,000 a month has an upper limit of AED 15,000 for all repayments. With a car loan instalment of AED 3,500 already running, no more than AED 11,500 is left for the mortgage instalment.

Loan to Value Limits for Expats and UAE Nationals

  • Expat, first home below AED 5 million: up to 80 percent of the value
  • Expat, first home above AED 5 million: up to 70 percent
  • Expat, second home or investment: up to 60 percent
  • UAE national, first home up to AED 5 million: up to 85 percent
  • UAE national, first home above AED 5 million: up to 75 percent
  • UAE national, second home or investment: up to 65 percent
  • Off plan purchase, any buyer: up to 50 percent

Only one property per borrower can be claimed under the first home category, and the maximum mortgage tenure is 25 years.

On an AED 2,000,000 ready first home, an expat can borrow up to AED 1,600,000 and needs AED 400,000 as the down payment before fees. The same unit bought off plan qualifies for no more than AED 1,000,000 of bank finance.

Off Plan Buyers: The Credit Check Comes at Handover

An off plan buyer who pays the construction instalments in cash may plan to fund the final payment with a mortgage. At Sorrento at DAMAC Lagoons, prices start at AED 680,000 with 50 percent due on completion in Q1 2030, so a unit at that starting price leaves AED 340,000 to pay at handover. For these DAMAC Lagoons apartments, the bank will judge the credit file the buyer holds in 2030, not the one from booking day.

A long construction period gives time to build a clean repayment record. It also leaves room for new loans, missed bills and fresh instalment plans to build up before any bank looks at the file.

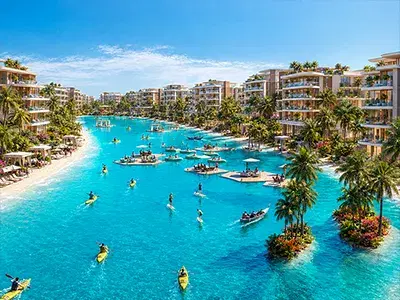
The same timing applies to the studio and 1 bedroom units at The Tropics at DAMAC Islands Dubai, where completion is set for Q4 2030. For buyers of these off plan apartments in Dubailand, the credit report that decides a handover mortgage is still about 4 years away, which makes the 12 month plan in section 7 worth starting well before the completion notice arrives.

Tabby and Tamara on Your Credit Report: BNPL and Mortgages

Buy now, pay later plans from Tabby and Tamara have been included in UAE credit reports since July 2026, for both existing and new customers. Account details, past transactions and repayment records from both providers are now visible to banks reviewing a mortgage file.

For a home buyer, small instalment plans that a bank could not see before now appear next to cards and loans. Several open plans at once show an underwriter that part of your monthly income is already committed. Clearing unused plans ahead of an application keeps your list of obligations short.

Credit Report Mistakes That Hurt Mortgage Approval in UAE

Avoid applying to several banks in the same week. Each lender that pulls your report as part of an application leaves an enquiry on it, and several recent applications make lenders cautious. Narrow the choice to one or two banks before submitting full applications.

Unpaid utility and telecom bills are easy to miss. Mobile, water and electricity accounts can be reported to the bureau, so a final bill left unpaid after moving out of a rented flat can show up on your file.

Returned cheques appear on the credit report and lenders treat them as a warning sign. Rent cheques and post dated cheques given to a developer both count, so a buyer on an off plan payment plan should keep the cheque account funded before every due date.

A sales agent's word about your eligibility means little until the bank confirms it in writing. Do not accept verbal confirmation of finance before paying a non refundable deposit.

How to Check AECB Credit Score Before a Mortgage

To check your AECB credit score, buy your score or full credit report through the bureau's official website or mobile app. You will need an Emirates ID, a UAE mobile number and identity verification, and a fee applies to each request.

  1. Download the bureau's app or open its website, then register with your Emirates ID.
  2. Complete the identity check and pay the fee by card.
  3. Choose the full report over the score alone, because only the report shows each account, payment delay and enquiry behind the number.
  4. Check every account, balance and personal detail, and raise a data correction request for anything wrong.

Disputes are free to file, and the bureau takes each one up with the bank or provider that reported the data. Corrections can take time to pass through the reporting lender, so file them well before any mortgage application.

How to Improve AECB Score Before Applying for a Mortgage

To improve your AECB score, settle any defaults first and then keep every repayment on time. Under 3i, residents who settle defaults may see their score improve within 6 months if repayments stay consistent. This is not guaranteed, and a new default can delay the recovery.

A 12 Month Plan Before You Apply

12 months before: buy the full report and settle every overdue balance it shows.

6 months before: pay every card, loan, telecom and utility bill on or before the due date, ideally through automatic payments.

3 months before: avoid new loans, cards and instalment plans, and do not max out the cards you have.

At application: have your salary certificate and recent bank statements ready, since lenders check them alongside your report.

If you have a bad credit history in the UAE, a mortgage is still possible, but give a clean repayment period time to show on your file first. New arrivals with little history should open one credit card early and clear it in full each month, so the bureau has repayment data to score.

What This Guide Is Based On

Score ranges, assessment periods and recovery rules reflect the official Credit Score 3i launch announcement. Loan to value, DBR and tenure limits reflect federal mortgage regulations in force in November 2026. Worked examples are simple calculations based on those limits.

Bank lending criteria, bureau fees and scoring methods can change after publication. Before committing money, rely on your own current report and written confirmation of finance from the lender.

Project prices, payment plans and handover dates are taken from the published project listings at the time of writing.

Thinking About Investing in Dubai Property?

Frequently Asked Questions

Can I get a mortgage in UAE with a low AECB score?

Yes, it is possible, but approval is harder. A low score may mean a smaller loan, a larger down payment or stricter terms, so clear overdue accounts and correct any errors first.

What is a good AECB score under the 3i model?

The bureau publishes no official labels for 3i scores, so there is no fixed number that counts as good. Aim for a score near the top of your range with no recent payment delays.

Do Tabby and Tamara plans affect a home loan application?

Yes. Banks reviewing a mortgage file can see plans from both providers as active commitments, along with their repayment record. Settling them early reduces the commitments a lender has to count.

Why do banks need my AECB report before approving a mortgage?

Banks must judge repayment capacity before lending, and the bureau report is their record of how you have handled loans, cards, cheques and bills. It shows obligations that a salary certificate cannot.

Can a settled default still stop my mortgage?

It can still weigh on your application, because lenders look at how recent the problem was. Steady repayments after settlement help, so give your record several months of steady payments before applying again.

Does checking my own credit report lower my score?

No. Checking your own score or report through official channels counts as a soft enquiry and does not affect your score. Only enquiries made by lenders during an application can have an impact.

Should I close old credit cards before a mortgage?

Not usually. Closing old accounts can shorten your visible credit history and may hurt your score. Keep long standing cards open, use them lightly and pay the full balance each month.

Is AECB the same as Etihad Credit Bureau?

Yes. AECB is the older name and abbreviation, and the federal bureau now operates as Etihad Credit Bureau. Banks and borrowers still widely use AECB to refer to it today.

Will paying off a car loan help my mortgage eligibility?

Usually yes. The monthly instalment drops out of your DBR calculation, leaving room for a larger mortgage, and the report shows one fewer active loan. Keep the settlement letter ready for the bank.

Can I use my home country credit history in the UAE?

Some newcomers can. Since 2023 the bureau has offered a cross border service that lets residents from certain countries share home credit records with UAE lenders. Coverage depends on the country and bank.
Sweety Ved
Sweety Ved
Property Consultant

Sweety Ved is a RERA-registered Property Consultant at Honey Money Real Estates (ORN: 28658) with 5+ years of transactional experience across Dubai's residential and short-term rental markets. She specialises in... Read More

Share Our Post

Related Projects

The Tropics at DAMAC Islands Dubai

The Tropics at DAMAC Islands Dubai

DAMAC
On Request
Studio & 1 BR
Coming Soon
Apartments
 Sorrento at DAMAC Lagoons Dubai
 Sorrento at DAMAC Lagoons Dubai

Sorrento at DAMAC Lagoons Dubai

DAMAC
0.680M*
Studio & 1 BR
341 - 879 Sq. Ft.
Apartments
DAMAC Tahiti 2 at DAMAC Islands 2

DAMAC Tahiti 2 at DAMAC Islands 2

DAMAC
3.8M*
4, 5 & 6 BR
2,185- 6,276 Sq. Ft.
Townhouses & Villas
The Verso by Reportage at Meydan Horizon Dubai

The Verso by Reportage at Meydan Horizon Dubai

Reportage
1.6M*
1, 2 & 4 BR
505 -1,851 Sq. Ft.
Apartments
Epoque by Reportage at Meydan Horizon Dubai

Epoque by Reportage at Meydan Horizon Dubai

Reportage
1.9M*
1 & 2 BR
545 - 1,115 Sq. Ft.
Apartments